Buying a home is an exciting milestone but also a significant financial commitment. Mortgage pre-approval makes a big difference in today’s competitive real estate market. Mortgage pre-approval shows sellers that you’re serious and helps you set a clear budget and avoid surprises later in the homebuying process. This guide will explain why mortgage pre-approval is essential and how to secure it quickly.
What is Mortgage Pre-Approval?
Mortgage pre-approval is a lender’s commitment to provide you with a loan up to a specified amount, based on an in-depth review of your financial situation through the mortgage underwriting process. This differs from pre-qualification, which only estimates how much you can borrow based on basic information like income and debts.
During pre-approval, lenders evaluate several key factors:
- Credit Score: Your credit score reflects your history of managing debt and influences the interest rate you’ll qualify for.
- Income: Lenders verify that you have a stable source of revenue sufficient to handle a mortgage payment.
- Debt-to-Income Ratio (DTI) compares your monthly debt obligations to your gross monthly income. The lower your DTI, the higher the loan amount you may qualify for.
- Assets and Savings: Lenders will review your savings to ensure you have enough for a down payment, closing costs, and any reserves in case of emergencies.
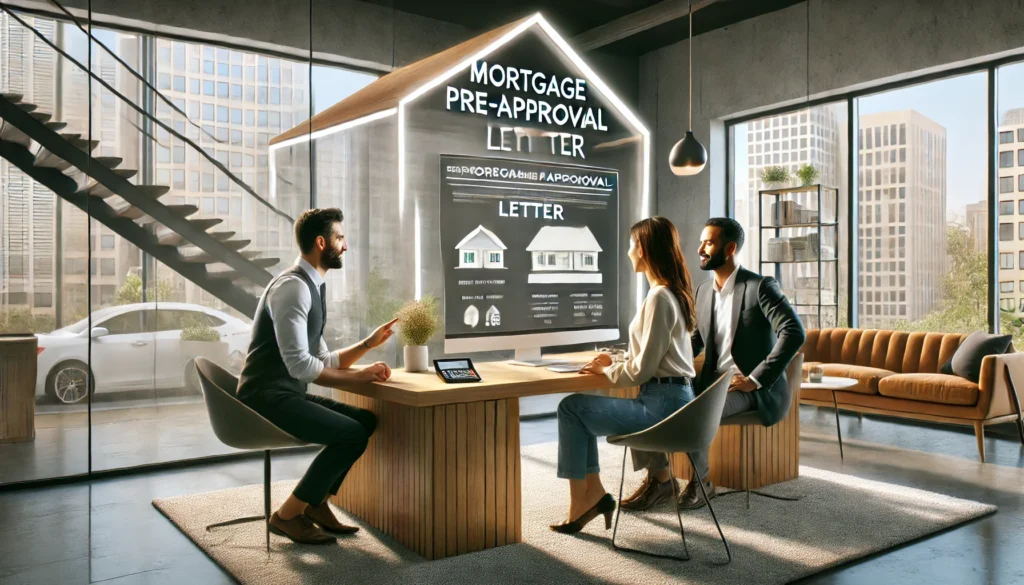
When you complete the pre-approval process, the lender provides a pre-approval letter, which you can present to sellers when making an offer. This letter outlines the loan amount you qualify for and proves you’re a serious buyer.
Why Mortgage Pre-Approval is Essential
Strengthens Your Buying Power
In a competitive housing market, sellers often prioritize offers from pre-approved buyers. A pre-approval letter signals that you’re financially capable of completing the purchase, giving you a significant advantage over buyers who haven’t gone through this process. Sellers are more likely to take your offer seriously, and in some cases, they may be willing to negotiate more favorably.
Sets a Clear Budget
Mortgage pre-approval clarifies how much house you can realistically afford. This helps you avoid wasting time on homes out of your price range, keeping your search focused and efficient. Knowing your budget will give you more confidence when shopping for a house and less likely to stretch yourself too thin financially.
Saves Time in the Buying Process
Pre-approval can streamline the homebuying process. Once pre-approved, many steps that could delay the mortgage process—like verifying your credit and income—are complete. The closing process will move quicker when you find a home you want to buy, as the lender already has much of the necessary information.
Getting Pre-Approved
Gather Your Financial Documents To begin the pre-approval process, you’ll need to gather several financial documents. Lenders require these to verify your financial stability and ensure you meet their loan criteria. Common documents include:
- Tax Returns: Lenders typically ask for two years of tax returns to verify your income history.
- Bank Statements: Your lender will want to see your current financial standing, including funds set aside for a down payment and closing costs.
- Proof of Income: This could include recent pay stubs, W-2 forms, or, if you’re self-employed, 1099 forms.
- Credit Report: Lenders will review your credit report to assess your creditworthiness and determine the interest rate you qualify for.
- Asset Statements: Any savings, investments, or retirement accounts you have will also be considered, as they demonstrate financial stability.
Steps to Apply for Pre-Approval
Once you’ve gathered your documents, the next step is to choose a lender. You can apply for pre-approval through banks, mortgage brokers, or online lenders. Using multiple lenders to compare rates is good, but be mindful of the time frame. Applying for various pre-approvals within 30-45 days generally counts as a single inquiry on your credit report, minimizing any potential negative impact on your credit score.
When you apply, the lender will run a credit check, review your financial documents, and provide you with a pre-approval letter if you meet their criteria. This letter outlines the loan amount, interest rate, and any applicable conditions, such as the requirement to maintain a certain credit score until closing.
Factors That Affect Pre-Approval:
- Credit Score: A higher credit score typically results in better loan terms, including a lower interest rate.
- Debt-to-Income Ratio (DTI): Lenders prefer borrowers with a DTI below 36%, with no more than 28% going toward housing-related expenses.
- Employment History: Lenders look for consistent employment over the past two years. Job changes or gaps in employment can raise concerns.
- Savings and Assets: Lenders will review your assets to ensure you have enough for the down payment, closing costs, and reserves.
What to Expect After Pre-Approval
A mortgage pre-approval is typically valid for 60 to 90 days. During this time, your financial situation shouldn’t change dramatically. If you wait over 90 days to make an offer on a home, or if your financial situation changes, you may need to go through the pre-approval process again.
What to Do After Getting Pre-Approved:
You can confidently start your lending search once approved. With a pre-approval letter, you’re in a stronger position to make an offer when you find the right home. Be sure to stay in touch with your lender during the search process, mainly if any changes in your finances occur, as this could impact the loan amount or terms.
Additionally, it’s crucial to avoid taking on new debt while you’re pre-approved. Even small changes in your credit or financial situation can affect your loan eligibility when it’s time to finalize your mortgage.
Why Pre-Approval Isn’t a Guarantee
While mortgage pre-approval indicates you’ll qualify for a loan, it’s not guaranteed. Pre-approval is based on your financial situation at the time of the application. If your financial status changes significantly—such as losing your job, taking on more debt, or having a dip in your credit score—the lender may reassess your application. This is why it’s important to maintain your financial health between pre-approval and closing. The home you choose may impact your final approval. The loan could be delayed or denied if the property doesn’t meet the lender’s appraisal requirements or title issues.
Conclusion
Mortgage pre-approval is a vital step in the homebuying process. It gives you a competitive edge, helps you set a clear budget, and speeds up the purchase process. By gathering your financial documents and applying with multiple lenders, you can secure pre-approval and confidently move forward. However, remember to maintain your financial stability after receiving pre-approval to avoid any issues at closing.