When buying a home, your credit score is more than just a number—it’s a critical factor that plays a pivotal role in determining your mortgage options and the overall affordability of your new home. A higher score can open doors to better mortgage rates, lower monthly payments, and increased bargaining power with lenders. Conversely, a lower score may limit your choices or lead to higher costs over the life of your loan.
Whether you’re a first-time homebuyer eager to step onto the property ladder or browsing the real estate market, understanding your credit score and its impact on your mortgage journey is essential. Your credit score affects the types of mortgages you qualify for and influences the interest rates you’ll be offered and the loan terms.
In this guide, we’ll discuss the credit score requirements for various types of mortgages, how to check and improve your score, and practical strategies for securing the best mortgage rates. With this knowledge, you’ll be better prepared to navigate the mortgage landscape and make informed decisions aligning with your financial goals.
Understanding Credit Scores and Their Impact on Mortgages
What is a Credit Score?
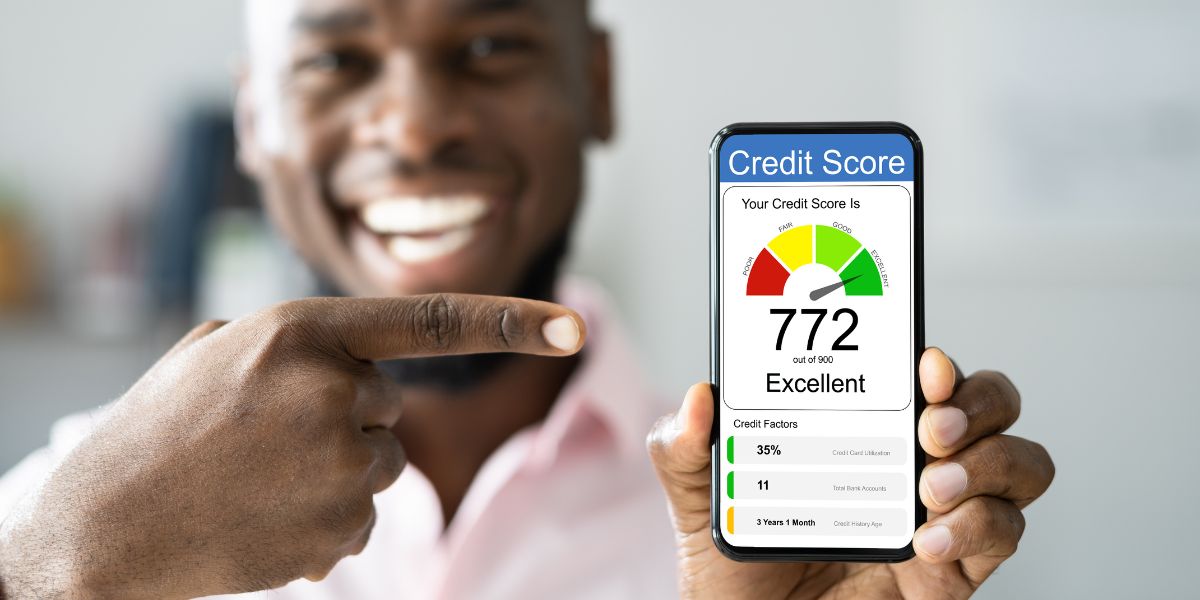
A credit score is a numerical representation of your creditworthiness based on your credit history. It ranges from 300 to 850, with higher scores indicating a lower risk to lenders. Your credit score is calculated based on several factors:
- Payment History (35%): This reflects whether you’ve paid past credit accounts on time. Late payments, collections, and bankruptcies negatively impact this portion of your score.
- Amounts Owed (30%): This factor considers the amount of credit you use compared to your total available credit, known as credit utilization. Keeping your balances low relative to your credit limit can positively impact your score.
- Length of Credit History (15%): This includes the age of your oldest account, your newest account, and the average age of all your accounts. A more extended credit history can help improve your score.
- Credit Mix (10%): This measures the variety of credit accounts you have, such as credit cards, mortgages, auto loans, and student loans. A diverse mix of credit types can improve your score.
- New Credit (10%): This considers the number of recently opened accounts and recent hard inquiries. Opening multiple new accounts in a short period can negatively affect your score.
How Credit Scores Affect Mortgage Approval and Terms
Different types of mortgages have varying credit score requirements. Here’s a breakdown of the minimum scores generally needed for popular mortgage options:
- Conventional Loans: Typically require a minimum credit score of 620. Borrowers with higher scores (740 or above) will likely receive better interest rates and terms, while those with lower scores may face higher rates and stricter conditions.
- FHA Loans: Insured by the Federal Housing Administration, these loans allow lower credit scores. A score of 580 is typically needed for a 3.5% down payment, while scores between 500 and 579 require a 10% down payment. However, due to the higher risk, not all lenders offer FHA loans to borrowers with scores under 580.
- VA Loans: These loans, guaranteed by the Department of Veterans Affairs, do not have a government-set minimum score. Most lenders prefer a score of at least 620 to mitigate risk. VA loans are an excellent option for veterans and active-duty military members.
- USDA Loans: Backed by the U.S. Department of Agriculture, these loans often require a minimum credit score of 640 for streamlined processing and favorable terms. They target rural and suburban homebuyers and may offer zero down payment options.
A higher credit score can lead to lower interest rates, reduced mortgage insurance premiums, and better loan terms overall. This is why it’s crucial to understand where your score stands and how you can improve it.
Checking Your Credit Score and Understanding Your Report
How to Check Your Credit Score
Checking your credit score is the first step in understanding your financial health before applying for a mortgage. You can obtain a free copy of your credit report once a year from each of the three major credit bureaus—Equifax, Experian, and TransUnion—through AnnualCreditReport.com. Online tools and credit monitoring services that regularly update your score are also beneficial. Knowing your score helps you gauge your mortgage options and determine if you need to take steps to improve it.
Understanding Your Credit Report
A credit report is a detailed record of your credit history. It includes information such as your payment history, outstanding debts, the length of your credit history, and recent credit inquiries. Reviewing your credit report allows you to identify any errors or discrepancies that could negatively impact your score. Common mistakes include incorrect personal information, accounts that belong to someone else, and outdated negative information. If you find any errors, dispute them with the credit bureau to have them corrected promptly.
Beyond checking for errors, understanding the contents of your credit report is essential to making strategic financial decisions. For instance, your report’s high debt-to-income ratio (DTI) might prompt you to pay down debts before applying for a mortgage. Similarly, a history of late payments could indicate a need for more stringent budgeting or bill management practices.
Improving Your Credit Score Before Applying for a Mortgage
Steps to Improve Your Credit Score
Improving your score can take time, but it’s one of the most effective ways to increase your chances of getting a favorable mortgage rate. Here are some strategies to help boost your score:
- Pay Your Bills on Time: Payment history is the most significant factor affecting your score. Pay all bills by their due dates, as late payments can significantly lower your score. Setting up automatic payments or reminders ensures you never miss a due date.
- Reduce Your Debt: Lowering your credit card balances and other debts can help improve your credit utilization ratio, which is the percentage of available credit you use. Aim to keep this ratio below 30%. Paying off credit cards and other revolving debts can quickly improve your score.
- Limit New Credit Inquiries: Each time you apply for new credit, a hard inquiry is recorded on your credit report, which can lower your score. To keep your score stable, avoid applying for new credit lines or loans before and during the mortgage application process.
- Correct Errors on Your Credit Report: Dispute any inaccuracies with the credit bureaus to ensure your credit report accurately reflects your credit history. Correcting errors can sometimes result in a quick boost to your credit score.
- Manage Your Credit Responsibly: Keeping older accounts open, even if they’re not being used, can help maintain the length of your credit history. Additionally, avoiding closing multiple accounts at once can prevent adverse effects on your score.
Timeframe for Credit Improvement
Improving your credit score takes time and effort. It typically takes several months to see significant improvements, especially if you are working on correcting errors or reducing substantial debts. Start the process early, ideally six to twelve months before applying for a mortgage, to give yourself ample time to make meaningful changes. The longer you work on building a solid credit history, the more your efforts will pay off in the form of better mortgage terms and lower interest rates.
Tips for Securing the Best Mortgage Rates Based on Your Credit Score
Strategies for Getting Lower Rates
Even if your score isn’t perfect, there are strategies you can use to secure a lower mortgage rate:
- Boost Your Credit Score: As mentioned, a higher score (750 or above) will help you qualify for the lowest interest rates. Improving your score before applying can pay off in the long term.
- Consider a Larger Down Payment: Putting more money down reduces your loan-to-value ratio (LTV) and can help you secure a better rate. A down payment of at least 20% can also help you avoid private mortgage insurance (PMI), reducing your monthly payment.
- Shop Around for Lenders: Don’t settle for the first offer you receive. Compare multiple lenders’ rates, terms, and fees to find the most competitive option. Different lenders have different criteria for credit scores, so shopping around can help you find the best deal.
- Look into Buying Discount Points: Some lenders allow borrowers to pay upfront fees or “points” to lower the interest rate over the life of the loan. This can be smart if you plan to stay in your home for a long time, as it reduces your monthly payment and total interest paid.
- Choose a Shorter Loan Term: Opting for a shorter loan, such as a 15-year fixed mortgage, often results in lower interest rates than a 30-year term. Although the monthly payments are higher, the total interest paid over the life of the loan is significantly less.
Following these tips can improve your chances of securing a favorable mortgage rate, even if your credit score isn’t perfect.
Conclusion
A strong credit score is a powerful tool in your home-buying arsenal, influencing your mortgage approval and the terms and rates you receive. By understanding how credit scores work, checking your score regularly, and taking steps to improve it, you can position yourself to get the best mortgage terms. Start today by reviewing your credit report, improving your score, and exploring all your mortgage options.
Ready to take control of your home-buying journey? Check out our beginner’s guide to buying a home. And don’t stop there—continue to explore more ways to enhance your financial readiness with our coming guide, “How to Improve Your Credit Score Before Buying a Home.”